What a lending platform operator needs from the software
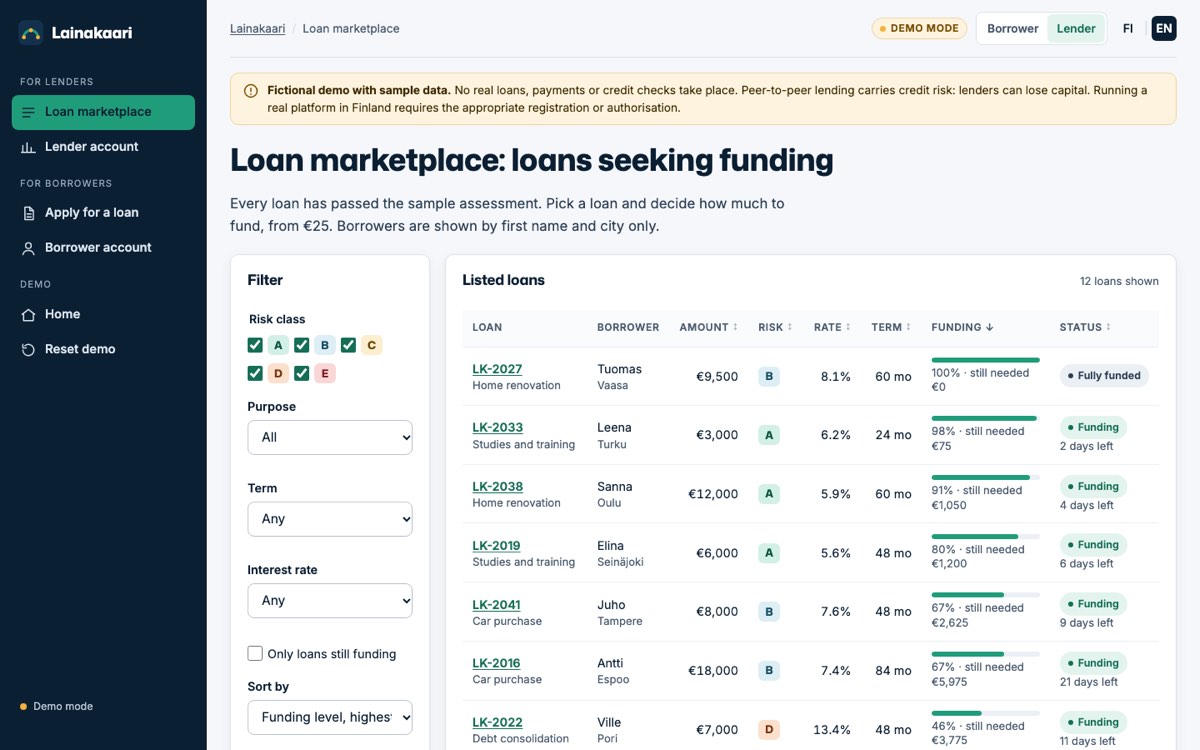
A peer-to-peer lending service has two groups of customers and one ledger. Borrowers need a clear application, a quick decision with reasons and a fixed instalment they can plan around. Lenders need to see risk class, rate, term and funding level before they commit, and then follow every payment that reaches them.
For the operator, the hard part sits behind the screens. Every instalment has to be divided between many lenders down to the cent, the figures have to reconcile with the bank account every day, and every decision has to be explainable to a customer or a supervisor later. Risks and costs must be visible before anyone commits money.
How the Lainakaari demo works
The application runs in five steps: loan, income and costs, identification, consents and assessment. Identification and the credit record check are labelled samples, and the demo never asks for an identity code. The sample scoring looks at employment, debt-service ratio, monthly buffer and loan term, then shows the risk class and the points behind it.
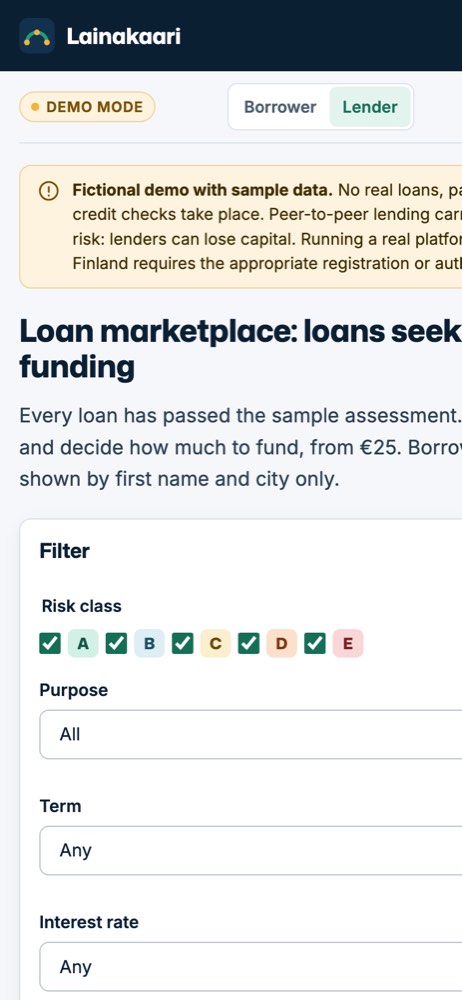
Approved loans appear in the marketplace with the borrower's first name and city only. A lender opens a loan, enters an amount and sees the monthly cash flow before fees and tax. The borrower account pays the next instalment on request, and the lender account shows the share that arrived.
The signature logic is the split. The instalment is an annuity rounded to the cent, and the last one clears whatever balance remains. Principal and interest are split separately in proportion to each share and rounded down, and the leftover cents go to the largest remainders, so the rows always add up exactly. All loans are sample data and no money moves.
What a production platform for a Finnish company adds
A real platform needs the appropriate registration or authorisation before it opens. In Finland, intermediaries of consumer peer-to-peer loans register with the Financial Supervisory Authority, and other models may need a licence. We do not give legal advice, so your legal adviser confirms what applies to you, and we build the software to meet those requirements.
On the technical side we add strong electronic identification through an identification broker, credit and income checks with the applicant's consent, customer due diligence and sanctions screening, and a payment integration with the bank or payment institution that holds client funds. Ledger entries reconcile with the bank daily and export to accounting.
Data protection is designed in from the start: GDPR records of processing, retention rules, encryption, role-based access and audit logs that show who viewed or changed a loan. Your staff get an admin panel for applications, listings, collections and customer service. The service runs in Finnish and English or Swedish, meets accessibility requirements and uses analytics only after consent. A dedicated team of ours maintains it, with security updates, monitoring and a test environment for every change.